Many Brazilians in the United States start working for themselves: in construction, cleaning, painting, landscaping, and services. Over time, the work grows, more clients come in, sometimes a helper, then a crew.
But in many cases, the business grows and the protection does not keep up. Everything still depends on one person: you. If you stop, the business stops, and so does your family’s income.
In this article, I share a few important steps for business owners in the U.S. who want to grow with more security.
1. Separate Business Money From Household Money
A very common mistake is using the same account for everything: getting paid by clients, buying materials, and paying the rent at home. This makes it hard to know how much the business really earns and can cause problems at tax time.
Having a separate business account is a simple step that brings organization and clarity. How to structure your company, such as an LLC or another type, and any tax questions should be handled with an accountant or attorney you trust.
2. Keep Savings for Slow Months
Business owners know income goes up and down. Some months are packed with work, and others are slow, like winter for people in construction.
An emergency fund for the business and another for the household help you avoid expensive loans during the slower months.
3. Plan for Your Retirement
People who work for large companies often have a 401(k) offered by their employer. Business owners do not: retirement is up to you.
Many business owners put this off, because every dollar goes back into the business. But starting early, even with a small monthly amount, makes a difference over the long term. There are different ways to do this. Some types of permanent life insurance, like an IUL, combine protection for your family with the potential to build value over time, according to the policy terms.
4. Protect the Business Owner
This is the point most business owners forget. Your business depends on your work, your contacts, and your experience. So ask yourself:
- If I get hurt on the job or become seriously ill, what happens to my income?
- If I pass away, could my family pay the bills and the business debts?
- If I have a business partner, what happens to my share?
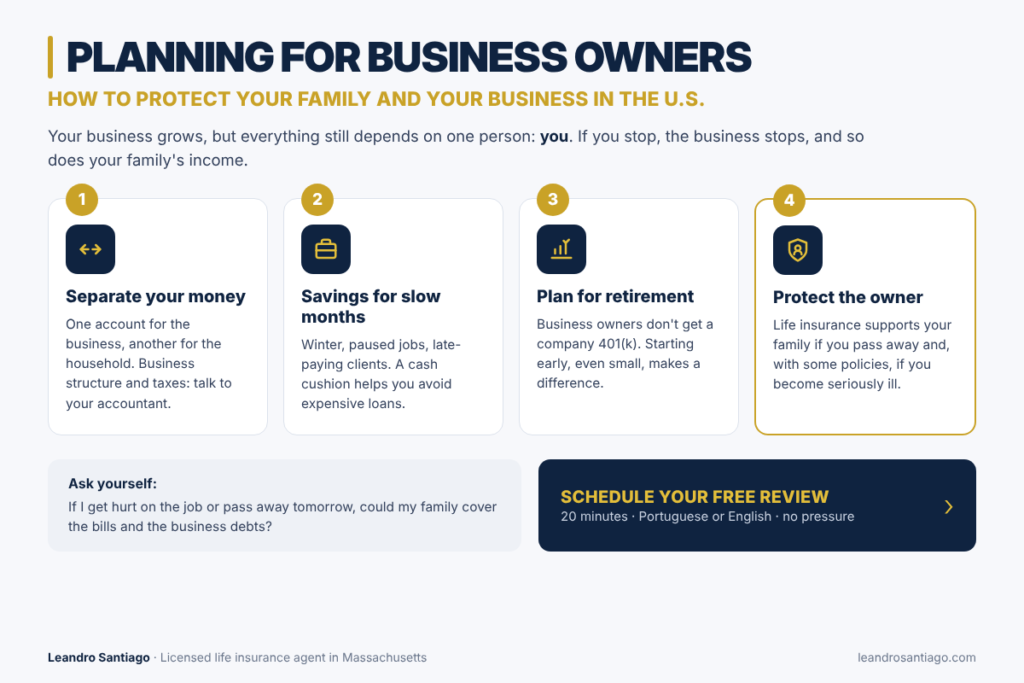
Life insurance exists for these situations. If you pass away, the insurance company pays an amount to the beneficiaries you chose, and some policies also let you access part of the benefit early in case of a critical, chronic or terminal illness, according to the policy terms. For business partners, life insurance can also be used together with an agreement between the partners, prepared with an attorney.
Grow With More Security
Growth is great, but a business that depends on one person is always one unexpected event away from stopping. Organizing your finances, keeping savings, planning for retirement, and protecting the owner are steps that help your work keep taking care of your family, no matter what happens.
If you want to know how our conversation works, read: What Happens During the Free Review? A Step-by-Step Look.
Want to see how to protect your family and your business? Click here to schedule your free review, a 20-minute conversation.
Prefer to talk on WhatsApp? Message me here.
This content is for educational purposes only and does not replace an individual review. Legal and tax questions should be handled with an attorney or accountant. Policy terms vary by insurance company and by the insured’s profile.
Updated: October 2026.