For almost every Brazilian who arrives in the United States, the first big financial goal is clear: build a Credit Score. We download the apps, watch the points go up month after month, and celebrate when the score passes 750 or 800.
There is no denying that good credit in the U.S. is great. It helps you finance a car at a lower rate, get cards with better limits and, one day, buy your own home.
But here lies a danger few people notice: confusing the ability to borrow money with financial security. A high score shows you pay your bills on time, but it does not guarantee your family will be okay if something unexpected happens tomorrow.
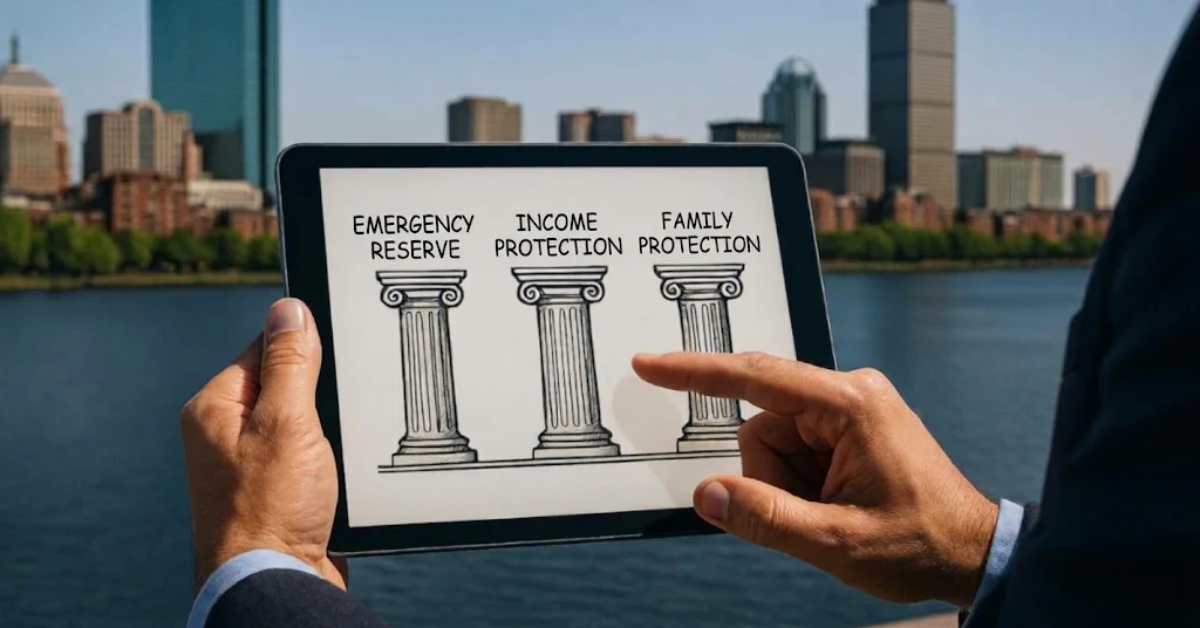
Your family’s stability depends on deeper foundations. In this article, I show you 3 important pillars for building a more solid financial structure in the U.S.
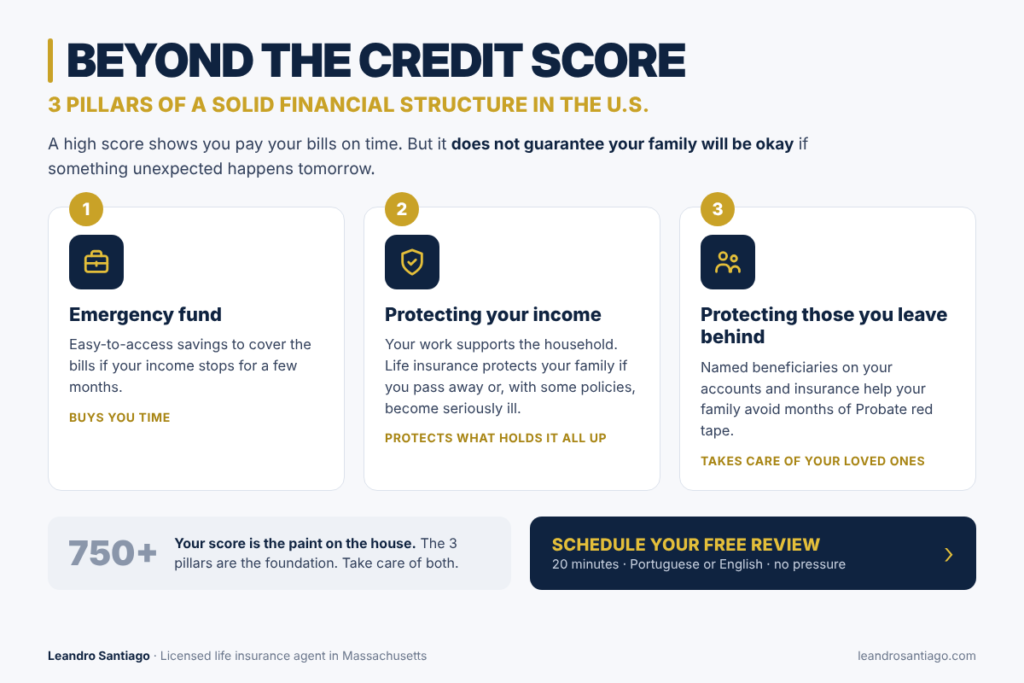
Pillar 1: Emergency Fund
The American lifestyle makes it very easy to spend on credit. It is easy to fall into the trap of paying for your routine with cards and loans, trusting that next month’s money will always come in.
But what happens if your income suddenly stops because of a health problem, a work injury, or a slow period in your industry?
The first pillar is having money available for emergencies. An 800 score does not pay the bills if you have nothing saved. Ideally, build an emergency fund based on your cost of living, kept in an easy-to-access account. This fund gives you time, peace of mind, and keeps you from turning to expensive loans at the first sign of trouble.
Pillar 2: Protecting Your Income
An emergency fund helps for a few months. But what if the problem is bigger, like a serious illness or your passing?
For those who depend on their own work, the family’s greatest asset is your ability to earn an income. It pays the rent or mortgage, the kids’ school, and the monthly bills.
The second pillar is protecting that income. That is what life insurance is for: if you pass away, the insurance company pays an amount to the beneficiaries you chose, so your family can move forward. Some policies also let you access part of the benefit early in case of a critical, chronic or terminal illness, according to the policy terms. It is protection that can help while you are still alive.
Pillar 3: Protecting Those You Leave Behind
You can have a great score, a home, and a healthy bank account. But without a plan for those you leave behind, your family may face months of red tape at a very difficult time.
In the United States, assets that are only in your name, with no named beneficiary, usually have to go through Probate, a court process that can be expensive and slow, before reaching your family.
A few simple steps help avoid this, like naming beneficiaries on your bank accounts and having life insurance with named beneficiaries, which is paid directly to them without going through Probate. To learn more, read: How to protect your family’s future in Massachusetts and avoid the ghost of Probate.
The Mistake of Building the House Starting With the Roof
Focusing only on your Credit Score and forgetting these 3 pillars is like caring only about the paint on the house while the foundation is cracked. At the first unexpected event, everything is at risk.
Credit is a useful tool, but it does not replace a foundation of protection for your family.
Building Your Foundation of Protection
The American system offers many opportunities, but it leaves little margin for error.
Having an emergency fund, protecting your income, and planning for those you leave behind are steps that help make sure the fruit of your work keeps taking care of your family, no matter what happens.
Want to see how these pillars apply to your situation? Click here to schedule your free review, a 20-minute conversation.
Prefer to talk on WhatsApp? Message me here.
This content is for educational purposes only and does not replace an individual review. Policy terms vary by insurance company and by the insured’s profile.
Updated: October 2026